The most popular question I get asked is how I manage to travel all the time. It's not that hard. You can quit your job, travel, and live remarkably, too.

Quit Your Job, Travel, and Live Remarkably
People ask how I manage to travel all the time. It's not that hard. You can quit your job and travel without needing much money.

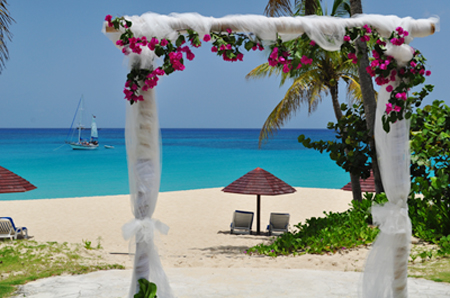
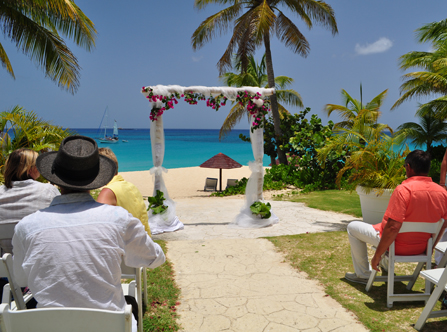
I just returned from 10 days in the Caribbean, where I was a bridesmaid in a friend’s wedding. This wedding felt surreal because the bride and I were together when she met her future husband.

They met three years ago. She and I were trekking in the Himalayas. My bum knee was slowing me down, so she reached the hut below Annapurna Base Camp several hours before I did. By the time I limped into camp, she and a tall, tanned Frenchman were tangled in each others arms.

They became inseparable from that moment on. We lost track of each other within a few days — I ventured south to India, they headed north to Tibet.

Eighteen months later, we reconvened in Central Australia to swap travel stories. We followed the same basic path — a wide loop across Southeast Asia, followed by a jaunt down to Australia — but our timing had always been a few months off. They would enter a country as I was leaving, or vice versa.

Yet we shared a bond from experiencing the same places and enduring the highs and lows of our distinct lifestyle. We carried our lives in our backpacks. We had no jobs, no home, no car. Only a map and a limitless imagination.

Click here to Grab a free pdf of this post

Another year passed by. I returned to the U.S. after two and a half years of overseas vagabonding. They moved to the Caribbean, where they work at an upscale pizza restaurant. When I flew to their wedding last week, we swapped stories.
The most popular question I get asked is how I manage to travel all the time. It's not that hard. You can quit your job, travel, and live remarkably, too.“I write a finance and lifestyle blog,” I told them, and they looked at me blankly.

“I mean, I write about how to live the life you want,” I said. Their faces brightened. The guy gave a slight nod.

“I write about how to use money to create your ideal lifestyle,” I said. “I write about cutting crap costs so you can spend lavishly on what you love most.”

The French groom smiled. His English is now smooth, solid, after three years of dating my American friend.

“Everyone asks how I could afford to travel for three years,” he said. “Once you decide to do it, it’s easy.”

How Could You Afford It?

When acquaintances hear how much we travel, they assume we’re rich. Or in debt. Or both.

These same friends don’t bat an eye when someone:

  • Buys a new car. I don’t care if it’s “just” a Honda Civic. Those cost $15,800 new.
  • Enrolls in grad school. Price tag: $40,000 or more.
  • Buys a home. Notice that a 20 percent down payment on a $250,000 home requires $50,000.

No one says, “OMG, you bought a car? How?” No one remarks, “You’re going to grad school? You much be rich!”
People don’t question spending thousands on conventional expenses.

But as soon as you spend a fraction of the cost of graduate school on an unconventional life — an exceptional life — questions and assumptions start popping out of the woodwork.

That doesn’t make sense.

If a new car is your deepest desire — if every morsel of your soul yearns for a brand-new Honda Civic — then by all means, buy one.

But if you dream of quitting your job, selling your car, packing your life into a backpack, and buying a one-way ticket to Egypt, cut ruthlessly in other areas of your life to make it happen.

Ignore Convention. Spend on Your Dreams.

It’s not hard to “give up” driving a nice car or living in a chic apartment. None of these so-called sacrifices are tough. You trade a few creature comforts for a life-changing experience

The year before I set out on my trip, I lived in a microscopic studio. I could wash the dishes while touching my bed. I’m not exaggerating. I could stand at the kitchen sink, kick one leg backwards, and rest my foot on the top of my mattress.

My Toyota had no seat belt. It was almost 25 years old, with 285,000 miles on it, and the fibers on the seat belt wore through. The rust hollowed out sections of the door. Snow blew onto my lap through rusty gaps as I drove. In hindsight, driving it wasn’t the safest decision.

But my bank balance was climbing at a frightening pace. Every month — heck, every week — I’d watch it scale higher and higher. It reached an amount with which I’d be comfortable traveling for one year. Then it doubled.

I was free. And what had I sacrificed? A car that’s a great conversation piece? A studio apartment that was perfect for cozy nights in?

I traded the mundane for the exceptional. And my life has never been the same.
I'm often asked how I can afford to travel. It's not hard. You can quit your job and travel without mountains of money. It's cheaper than you think.

You Might Also Like

  • | | |

    #749: How a Blind Man and his Guide Dog Survived Sept. 11 — and What His Mindset Can Teach Us, with Michael Hingson

    On September 11, 2001, Michael Hingson was on the 78th floor of the World Trade Center’s North Tower with his guide dog, Roselle, when the first plane hit. Over the next hour, they walked down 78 flights of stairs together, calm the entire way. Michael later wrote about that day in Thunder Dog, a New…

  • | | | | |

    #748: Q&A: My Dream Job Won’t Wait If I Take a Family Gap Year. Do I Quit Anyway?

    “So to me, this is not a money management question.” That’s what I told Jamie, a 42-year-old PA with $686,000 saved, right after she described her plan: quit the job she loves and take her husband and kids on a family gap year while they’re still young enough to remember it. She wasn’t asking if…

  • | |

    #719: Your Office Is Making You Sick, with Dr. John La Puma

    Did you know that the average modern office worker spends a staggering 93% of their life indoors? While the hustle to achieve financial independence often pushes us to put our heads down, stare at monitors, and clock endless hours inside a climate-controlled box, we might be accidentally sacrificing our long-term cognitive and physical health in…

  • |

    #606: Can You Really Afford to Die? – with Hospice and Oncology Nurse Suzanne O’Brien

    Hospice nurse and end-of-life educator Suzanne O’Brien joins us to discuss the financial realities of dying in America — and they might surprise you.

    Remember Aretha Franklin?

    Her handwritten will was found in her couch cushions after she passed away. Despite her substantial wealth, this simple document was legally upheld. It’s a powerful reminder that having any form of will is better than none at all.

    But there’s more to worry about than just having a will or trust. The costs of aging and dying can add up fast.

    Long-term care costs can quickly deplete even substantial savings. Suzanne shares a story about a couple with over $5 million who were shocked to learn how quickly 24/7 care for dementia would consume their nest egg.

    Traditional funerals average between $7,000-$11,000, but there are much more affordable alternatives:

    • Home wakes and natural burials can cost just a few hundred dollars
    • Water cremation offers an environmentally friendly option
    • Whole body donation to medical institutions costs nothing while contributing to education

    Planning ahead gives you control over these decisions and spares your loved ones additional stress. Multi-generational living arrangements can also reduce caregiving costs and address concerns like isolation and safety for aging family members.

    Suzanne also shares stories about the emotional side of dying. Did you know some people seem to choose when they go? She tells us about a 99-year-old woman in a coma who somehow held on for days until she turned 100, then passed away that very night.

  • | |

    #596: First Friday: Tariffs Grab Headlines, But These Financial Changes Nobody Is Talking About Will Impact You Too

    Yesterday, the White House rolled out the biggest tariffs in a century, sending markets into their worst decline since the pandemic. While headlines focus on supply chains and inflation, there are important economic stories you’re not hearing about.
    During the first half of this month’s First Friday episode, we dig into what nobody’s talking about. And in the second half, we grapple with the headlines.
    Student loan rules just changed again. The government added new limits to Public Service Loan Forgiveness. Right now, 9.2 million people — one in five borrowers — can’t keep up with payments. Many folks don’t even know payments started again after that four-and-a-half-year break.
    S&P just dropped a new report that backs what smart money already knows: index funds crush actively managed funds 90 percent of the time. Even with all those tech stocks dominating the market, you still come out ahead with simple indexing.
    You know who’s gobbling up the mortgage market? Rocket Companies. They just bought both Redfin and Mr. Cooper. They’ll handle one of every six mortgages in America. They’ve positioned themselves at every step of the homebuying journey — from when you search for homes on Redfin to financing and monthly payments for the next 30 years.
    The White House just made a surprising move with Bitcoin. They’re setting up a Strategic Bitcoin Reserve to hold coins long-term. They’re also creating a separate stockpile for crypto they seize in legal cases. Pretty clear signal that Bitcoin stands apart from other cryptocurrencies.
    In the second half, we dive into those significant new tariffs making headlines.
    The S&P 500 dropped 4.8 percent on Thursday — we haven’t seen a drop like that since the pandemic. The new rules put at least a 10 percent tariff on everything coming into the country. Then come the “reciprocal” rates: 20 percent for European goods, 27 percent for items from India, and a combined 65 percent for Chinese imports.
    We bring in Bob Elliott to make sense of this situation. His credentials are impressive — he spent 13 years at Bridgewater Associates (the world’s largest hedge fund), served as head of Ray Dalio’s investment team, and graduated magna cum laude from Harvard.
    During the 2008 crisis, he directly advised the Treasury, Federal Reserve, and White House.
    Bob offers a reality check about bringing back manufacturing jobs: you can’t build factories overnight. These investments take years, and companies hesitate to make 30-year commitments when policies change every few months.
    Bob breaks down four economic forces all hitting at once: tariffs jacking up prices, government cutting spending, tax policies on hold, and the Fed moving like molasses. Put them together? Yikes. He doesn’t sugarcoat it — the short-term outlook looks “pretty negative.”

  • |

    #594: How to Travel on $75 Per Day, with Nomadic Matt Kepnes

    Ever wonder if you could afford to travel for months at a time? According to Nomadic Matt, who’s visited more than 100 countries over the last 19 years, you can see the world on just $75 a day. That’s about $27,375 per year, less than many people’s current cost of living.

    Matt Kepnes, better known as Nomadic Matt, joins us to challenge common assumptions about travel costs. He explains that long-term travel can actually be cheaper than staying home. 

    When you’re traveling, you shed many regular expenses that eat into your budget back home, like car payments, home insurance, and utility bills.

    The key is to “travel like you live,” as Nomadic Matt puts it. This means using public transportation instead of taxis, shopping at local markets, and seeking out free activities — just like you might do in your hometown.

    It’s not about staying at five-star resorts, but experiencing destinations authentically while keeping costs reasonable.

    Nomadic Matt also breaks down several travel myths. The old advice about booking flights on Tuesdays? Outdated in today’s algorithmic pricing world. Using incognito mode to get better flight prices? No evidence supports this idea. 

    He does confirm that booking round-trip flights often costs less than one-way tickets, even if you don’t use the return portion.

    For those interested in credit card points, Nomadic Matt recommends choosing cards based on your specific travel goals rather than chasing the most popular options. Consider which airlines you use most and what perks you’ll actually take advantage of.

    The pandemic has transformed travel in significant ways. While prices have increased and some budget travel services have disappeared, new opportunities have emerged — especially for remote workers who can now take advantage of digital nomad visas to live abroad while maintaining their income.

    Whether you’re planning a two-week vacation or dreaming of becoming location-independent, Nomadic Matt’s practical advice shows how international travel is more accessible than you might have thought.