Is it worth going to grad school and taking on extra student loan debt? Only if it will help you achieve your dreams. I answer this reader question here.

Should I Go to Grad School?
Is it worth going to grad school and taking on extra student loan debt? Only if it will help you achieve your dreams. I answer this reader question here.

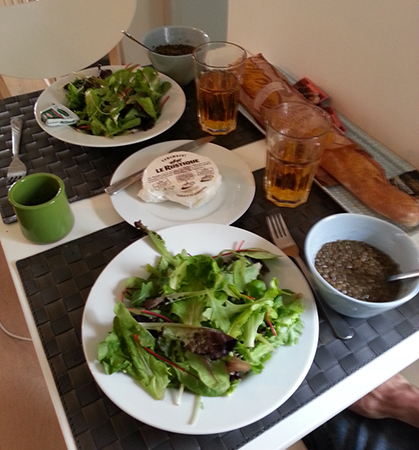
Lunch in ParisI’ve been in Paris for more than a week, and I’m reminded of how little money you need to have an amazing experience.

This morning I ate a fresh baguette (88 cents) with cheese and olives, and sipped a homemade cappuccino in my living room. This afternoon I’m taking a long walk to a local park, where lilies are in full bloom.

Today’s spending: Almost zero. Enjoyment: Complete.

****
Welcome to the latest edition of Reader’s Ask. Today I’m featuring two questions: one from a reader who is debating whether or not to attend grad school, and the other from someone who has a logistical question about travel and money.

Reader Question #1:

I’m 24 years old. I have a marketing job making about $40k per year (before taxes), half of which I live on, the other half goes into a savings account, which I use for my student loan payment and my Roth IRA contribution. I have about $18k in student loan debt. I have about $15k saved in a Roth IRA, and a few thousand in a 401k plan. I’m happy with what I’ve been able to accomplish so far, but I want to do more.

I’ve been accepted into the MBA program. Total tuition and fees will run me about $15,000. The motivating factor for me wanting to get my MBA is to be able to teach business and marketing classes at a University. In my area, these positions are typically paid around $50,000 per year. Not a bad rate of return, invest $15k and earn $10k more in just one year….. BUT is it worth taking out the extra student loan debt? (This would take my total debt up to around $35k — yuck!)

Afford Anything’s Answer:
You’ve stated that your motivation is to teach business/marketing classes at the college/university level. That’s key information, and its good to hear. Getting a masters degree is a mandatory prerequisite to getting that job.

If you had written to me and said, “I want a marketing position at a company,” I’d be a bit more hesitant about recommending that you go to grad school. After all, you can get a marketing job with your bachelor’s degree, and then climb your way up by being an awesome performer. Once you’re on-board with the company, most people won’t know what your highest level of education is. And your rockstar performance at the company will matter more than your education.

But teaching at the college level is different — the degree is literally a requirement; it’s an unavoidable price of entry. So if that’s what you really want to do, then I think that you should go for it.

BUT — and here’s the but —

First I want you to ask yourself one question: Is this your dream?

Don’t take that question lightly. Are you going to want this same dream (teaching at the college level) within two years, when you graduate? Do you want it badly enough that you’re willing to sacrifice traveling, delay investing, delay buying a home and throwing a wedding and having kids, for the sake of pursing this dream?

If your answer is yes, then absolutely go for it. I have no objection to people consciously making sacrifices in other areas of their life for the sake of pursuing a dream. In fact, I think that’s admirable. Everyone who has done anything noteworthy has made plenty of sacrifices along the way.

My only “beef” is with people who assume they should go to grad school because they’re “expected” to, or because they’re dissatisfied with their current job, or because their friends did it. That’s not sacrifice on behalf of a dream … that’s sacrifice for no real good reason, other than succumbing to social pressure.
money you dont have

Reader Question #2:

How do you pay for things when you’re traveling? Is it safe to carry that much cash around?

The more you’re off-the-beaten-path, the more likely cash is your only choice.

If you’re in Burma, buying a cup of tea from a market stall, you’ll need cash. But in more developed countries, you’ll be able to swipe plastic.

Don’t assume that “developed countries” is synonymous with the Western world. There are plenty of highly developed countries across the Middle East and Asia. The United Arab Emirates, Egypt, Malaysia – these nations, especially their major cities, are far more advanced than you might imagine. (The flashy wealth in Kuala Lumpur is unbelievable. It’s what I imagine Beverly Hills to look like.)

So, onto the second part of your question – how do you keep your money safe? Credit cards give you the highest levels of fraud protection, so use it when you can. When you use cash, withdraw money from an ATM rather than going to a moneychanger. You’ll get the best exchange rate.

Withdraw ONLY as much cash as you need for about a week. Put the majority of that into a “money belt” that you wear under your pants. Stash only one day’s worth of cash into your wallet. That way, if you get pick-pocketed, you’ll only lose a day’s bills.
You Might Also Like

  • | | | | | | | |

    #542: Are We All Financial Hypochondriacs? Why We Feel Broke, Even When Our Bank Accounts Are Full

    Ever feel like you’re never doing enough with your money, even when your finances look good on paper? 

    You’re not alone. 

    Katie Gatti Tassin, host of the Money with Katie podcast, dives into a phenomenon called “money dysmorphia” in today’s interview.

    She shares how she got flooded with responses when she asked her listeners about money dysmorphia. Folks with hefty savings and investments still worry they’re not doing enough. It’s like they’re always waiting for the other shoe to drop.

    Where does this come from? Katie points to a few culprits. Social media is an obvious scapegoat. But traditional media plays a role too. Think about all those TV shows where “normal” families live in massive houses and drive fancy cars. It skews our perception of what’s average.

    Location matters too. Katie talks about how moving from Dallas to Fort Collins changed her spending habits. Different cities have different vibes and social norms around money.

    The conversation takes an interesting turn when Katie shares her own experience buying a Porsche. She felt conflicted, worried her FIRE (Financial Independence, Retire Early) community would judge her. It highlights how even personal finance experts grapple with these issues.

    They also touch on how the pandemic shook up financial priorities. When faced with uncertainty, some people realized saving for a far-off future might not be the only goal worth pursuing.

    Katie and Paula discuss the importance of balance. It’s good to save, but not at the expense of living your life now. They suggest seeking out voices in the personal finance world to get a more rounded perspective.

    Travel comes up as a way to gain financial perspective. Seeing how people live in other parts of the world can make you appreciate what you have or show you where your own country could improve.

    Katie and Paula offer food for thought on how to navigate our complex relationship with money. It’s a conversation that might make you think differently about your own financial mindset.

  • |

    #322: Ask Paula – I Want to Retire at 50; How Do I Bridge the Gap?

    [smart_track_player url="https://traffic.libsyn.com/secure/paulaandjaymoney/AA322.mp3" title="Ask Paula - I Want to Retire at 50; How Do I Bridge the Gap?" artist="Paula Pant" social="true" social_twitter="true" social_facebook="true" social_gplus="true" social_linkedin="true" social_stumble="true" social_pinterest="true" social_email="true" ]

    Jess wants to reach financial independence by the time she’s 50. But she’s worried that she doesn’t have enough money in cash or taxable brokerage accounts to bridge the gap in her first few years of retirement. What moves should she make, if any?

    Yisell wants to invest money now. Should she cash out her $70,000 pension in hopes to generate more than the $1,000 per month she’s guaranteed from it?

    Abbey is 22 and she would like to go back to graduate school for nurse anesthesia. Should she save up and pay for it in cash, or invest her money and take out federal loans?

    Eliana enjoyed our interview with Paul Merriman on the two-fund portfolio. She’s curious about what growth stocks and value stocks are, and how they fit into a passive index fund investing strategy.

    Finally, Sneezy wants to know: why aren’t stocks a good hedge against inflation?

    My friend and former financial planner, Joe Saul-Sehy, joins me to answer these questions on today’s episode. Enjoy!

  • |

    How Radically Redefining ‘Necessary’ Spending Can Set You Free …

    This has been a big week: I had dinner with my biological sister, whom I haven’t seen in 7 years. (I was adopted.) But this isn’t a blog post about cross-country family reunions. It’s a post about a magical thing called discretionary income, the key to a portal of incredible opportunities. Discretionary money lets me…

  • |

    How the “Diderot Effect” Can Change Your Life …

    In the 18th century, a French writer named Denis Diderot received a gift: a beautiful scarlet dressing gown. The fabric was gorgeous. The colors were rich. The craftsmanship was spectacular. Diderot immediately threw his tattered old gown away. He didn’t need it anymore. His new gown was breathtaking. Of course, he needed to make a…