the problem with “i’ll just keep working”
Welcome to Three Things Monday — three things worth knowing as you start the week.
“i’ll just keep working?”
I was recently talking to someone in his 40s who hadn’t yet saved much for retirement.
His explanation was, “I’m not really interested in retiring. I’ll just keep working.”
That’s cool if you want to do that — but that’s also a cope, if it’s keeping you from building a portfolio.
Nearly half of retirees left their jobs earlier than planned in 2025, according to a major annual retirement confidence survey.
They cited factors beyond their control, like healthcare needs or involuntary layoffs, as the primary reason. They retired at a median age of 62.
“There is also a difference between how workers think they will stop working and how it actually pans out,” the survey said. “While almost half of workers think they will have a gradual transition to retirement, three in four retirees fully stopped working.”
The survey, now in its 36th year, also found that fewer people (among both retirees and workers) rate their finances as ‘very good,’ as compared to previous years. Results came from a sample of 2,544 people.
The takeaway? Build multiple streams of residual income. The reality is that retirement isn’t always voluntary. And so you want to be prepared just in case something happens.
There’s freedom in being able to walk away. (And even if you choose to continue working, there’s freedom in knowing that you could walk away at any moment if you wanted to.)
medium-term rentals?
Many people think in terms of either traditional 12-month leases, or short-term rentals like Airbnb.
But there’s a third option that’s not often considered — and in some ways, it blends the best of both worlds.
Medium-term rentals (2-11 months) are furnished rentals for people who need to stay for a few months. Think traveling nurses, visiting scholars, people traveling for special events, projects, or corporate needs.
The returns beat long-term rentals — often by 20 to 30 percent — without the constant turnover of running an Airbnb.
In Tuesday’s podcast episode (yep, that’s tomorrow … or, by the time you’re reading this, it’s probably today), we’re going to do a deep dive into the pros, the cons, the considerations.
It’s an exploding market, and in some ways, this particular moment in time — 2026 in medium-term — has the vibes of Airbnb in 2012, as we talk about in the episode.
announcements
First, I recently found out that someone with the email address paulapant.mail [at] gmail [dot] com is sending people emails pretending to be me.
THIS IS NOT ME.
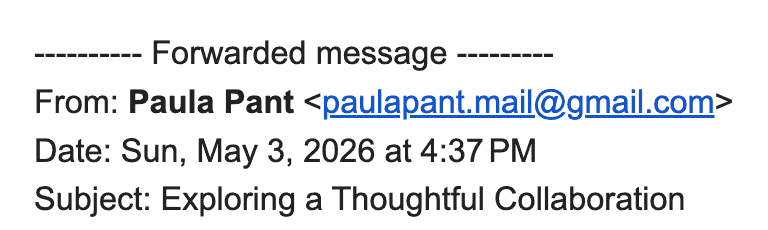
This has been happening to a lot of people who talk about personal finance — someone I know recently received an email from someone pretending to be Dave Ramsey (but it came from a Gmail account.)
This is the second time that someone has spoofed me via email, and it’s getting worse, because the tone, the voice — it sounds like me. They clearly dumped my entire website into AI and made a pretty decent imitation.
This is important enough and creepy enough that I want to flag it in a major way — because it’s not just me that’s getting spoofed, it’s a lot of personal finance creators.
And when scammers are specifically targeting personal finance, it’s because they want your money.
So please — be aware that anything you get from me is always going to have an [at] affordanything [dot] com email address.
And if you get something from anyone else who’s a personal finance creator, whether it’s (spoofed) “Dave Ramsey” or (spoofed) “Ramit” or whomever else, please triple-check the email address and trust your gut if anything feels a little off.
This is the Sixth Edition of Three Things Monday.
Know someone who cares about their net worth? Forward this their way.
If you’re reading this as a forward — welcome. You can subscribe for free here.