Stop obsessing over avocado toast
Welcome to Three Things Monday — three things worth knowing as you start the week.
Let’s begin!
“how do i save more money?”
Let’s go back to one of the most basic questions in personal finance: “How do I save more money?”
I talked about this on stage at Texas A&M Texarkana during a live podcast taping, and I want to share that answer with you.
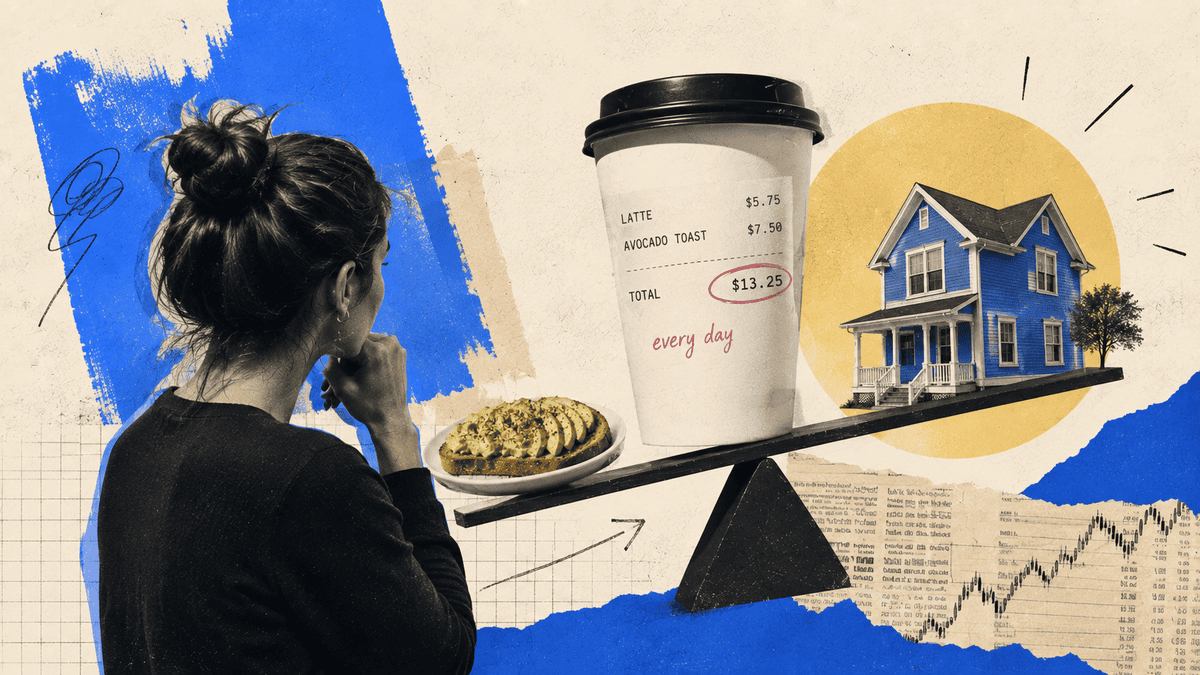
The cliche answer is: “Stop ordering avocado toast.” I think that misses the point.
Here’s a more useful way to think about it:
There are fixed costs: rent or mortgage, and installment loans like car payments or student loans. These are the numbers that don’t budge without a LOT of effort (like moving or refinancing).
Then there are variable costs, which fall into two categories.
There are variable costs for necessities – groceries, utilities.
And there are variable costs for discretionary items – avocado toast, lattes. Most advice tends to focus on cutting variable discretionary spending.
The goal becomes: spend less on discretionary items. From that come tactics (budgeting hacks) and strategy (mindset reframes, environmental cues and triggers).
But this puts the focus in the wrong place.
Cutting discretionary spending is low-friction, which is why it’s so popular. There are few barriers to, say, not ordering that second beer, or not buying another cashmere sweater. You just don’t do it.
Yes, there are mindset shifts and tactical tools. But at the end of the day, each decision you make is in isolation. Whether you skip the beer on Friday has nothing to do with whether you buy the sweater on Monday.
And because these decisions are frequent, they rely on ongoing willpower. You have to choose again and again.
This means it gets exhausting to say “no” a hundred times, but also, it becomes the focus of habits, systems, environment. It becomes the focus of budgeting because there are so many tactics / strategies around it, due to its frequency. This is, in part, why it comes to dominate the conversation.
And whatever decision you make, the impact on your budget is instant. So ironically, there’s some immediate gratification that comes from making a choice, whether or not you buy the beer/sweater.
If you buy the beer/sweater, you get the immediate gratification of the purchase. But if you’ve deeply internalized a desire to save, you get the identity boost of reinforcing that you’re a great saver. There’s immediate payoff either way.
To recap, focusing on variable discretionary costs is: (1) low-friction; (2) frequent; (3) immediate. This is why it gets so much focus.
But unless you’re a heavy spender, how much does this actually move the needle? For many people, discretionary spending is a relatively small slice of their overall budget.
By contrast, fixed costs tend to eat up the biggest proportion of your expenses.
But we don’t talk about these as much, because changing these is high-friction.
To change your rent, you would literally have to move. To change your car payment, you might literally have to sell your car and buy a clunker.
It’s a pain, and people often respond to these suggestions with a hundred reasons why they “can’t.” But this is where you see the biggest impact.
The problem is that changing fixed costs are one-time decisions. These new choices often take months to implement. And so you get neither frequency nor immediacy, and it’s high-friction. That’s why changing fixed costs gets less attention.
But it’s more of a needle-mover. (For two reasons: (1) because it’s a bigger chunk of your budget, and (2) because once you’ve locked it in, you’ve recalibrated your baseline.)
If you want small wins, cut discretionary spending.
But if you want meaningful change, focus on fixed costs.
“where do i put my money?”
This is another question I answered during our live taping at Texas A&M.
It’s a framework I use with beginners, so I want to share it with you — something you can pass along to someone just getting started.
Imagine a variety of glassware: coffee mugs, champagne flutes, martini glasses, wine glasses, shot glasses, plastic red Solo cups.
These represent your various accounts: 401k, IRA, HSA, taxable brokerage, checking, and savings.
Then there’s the actual drink: coffee, tea, champagne, vodka, wine, water, milk, juice. These represent the assets inside of the accounts — cash, CDs, index funds, mutual funds, individual stocks.
There are certain assets that are typically held inside certain accounts — champagne normally goes in a champagne flute. This is called asset location.
(If you want to go deeper, here’s an in-depth guide to asset location, for people at an intermediate-plus level.)
I sometimes talk to beginners who say things like, “Well, I don’t trust the market, so I’m not going to open a 401k.” This is the analogy I use to explain what they’re misunderstanding.
The 401k is not the market. The 401k is just the coffee mug.
If you don’t trust the market, you could still open a 401k, get the employer match, and hold bonds or even cash.
I wouldn’t recommend that as a long-term investment strategy. But getting the employer match is better than not getting it, so it’s a solid first step.
I’ll also talk to beginners who say, “Well, I’m excited about trading and crypto, so I’m going to open a Robinhood account.”
And I’m like, “Cool, do you have a Roth IRA?”
And they say, “No, that’s boring.”
But they can hold individual stocks and crypto ETFs inside a Roth IRA if they want to. (Again, I’d be cautious about too much of that as a long-term strategy — but it’s an option.)
The point is not to conflate the container with what’s inside it.
So when you’re deciding “where to put your money,” you’re really making two separate decisions: (1) which account to use, and (2) what to invest in inside that account.
Which type of real estate investor are you right now?
Over the last few weeks, I’ve been fielding some interesting questions about real estate on the podcast. I’ve also been having lots of conversations with people about whether it’s a good time to invest in rental properties.
nd I’m curious where you stand?
I’d love it if you could help me with a little market research so I can develop some new content in the coming weeks.
Please let me know:
This is the Fourth Edition of Three Things Monday.
If you know someone who’s starting to take their finances seriously, forward this their way.
And if you’re reading this as a forward — welcome. You can subscribe for free here.